
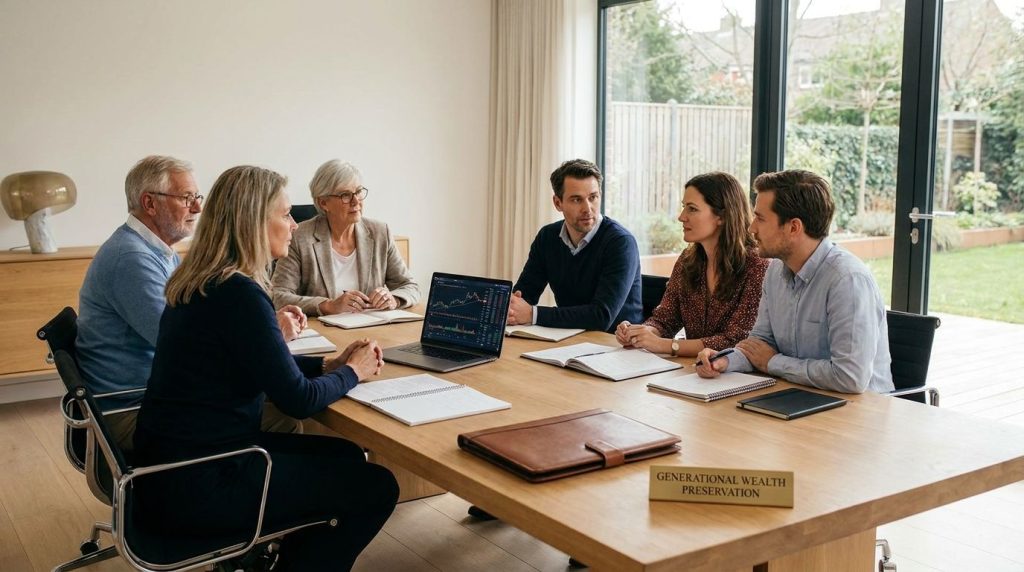
Financial education is one of the few tools that can help you protect wealth before it is built, while it is growing, and after it is transferred. If you want generational wealth to last, you need more than assets on paper, you need financially capable heirs, clear planning, and repeated family communication.
You’re dealing with two forces at the same time: a large transfer of money between generations and a persistent gap in financial literacy across the United States. This article shows you how those forces meet, where families usually break down, and what you can put in place to preserve money, reduce conflict, and create stewardship that holds up over time.
How Does Financial Education Affect Generational Wealth Preservation?
Financial education shapes the decisions that determine whether wealth compounds or leaks away. When you understand saving, debt, investing, insurance, risk, and financial decision-making, you’re better equipped to manage money with discipline instead of reacting to pressure, fear, or family confusion. That matters before any inheritance arrives, and it matters even more after a transfer, when the margin for error gets thinner.
The strongest public research on this point is consistent. The TIAA Institute and Global Financial Literacy Excellence Center Personal Finance Index describes financial literacy across eight common activities: earning, consuming, saving, investing, borrowing, insuring, understanding risk, and gathering information. Those are not abstract topics. They are the daily operating skills behind wealth preservation, and when those skills are weak, inherited assets often face poor allocation, overspending, avoidable taxes, and unmanaged family conflict.
The Financial Industry Regulatory Authority Foundation’s National Financial Capability Study tracks how people actually behave with money, not just what they say they know. Its national findings show that many households are under greater pressure even when income appears stable, and the share of adults with enough money set aside to cover three months of living expenses fell to 46%. That tells you something useful: education matters, but education without systems, habits, and accountability doesn’t hold the line for long.
If you want wealth to survive beyond one generation, you need to treat financial education as operating discipline. You’re not teaching people how to “be interested in money.” You’re training them to make repeatable decisions under stress, over years, with real tradeoffs. That’s where wealth is either preserved or quietly lost.
What Is The Great Wealth Transfer, And Why Should You Care?
The Great Wealth Transfer refers to the large movement of assets from older generations to spouses, heirs, and charities over the coming years. One of the most cited estimates, referenced in mainstream financial coverage, puts the total at about $84 trillion moving in the United States through 2045, with roughly $72 trillion expected to go to heirs and nearly $12 trillion to charity. You don’t need a headline to tell you this matters. You just need to recognize what happens when money changes hands faster than knowledge does.
If you’re advising a family, building your own estate plan, or preparing heirs, this transfer is not just a legal event. It’s an education event, a governance event, and a behavior event. A beneficiary who inherits assets without understanding taxes, trust structures, cash flow discipline, risk tolerance, or the family’s intentions is far more likely to make costly decisions early. That can happen even in families with substantial net worth and well-drafted legal documents.
You also need a balanced view. Commentary from the CFA Institute pushes back on inflated expectations around the Great Wealth Transfer and notes that many people may overestimate what they will personally receive. That matters because false expectations can distort family conversations long before any transfer occurs. When heirs assume wealth is coming, but have no clarity on amount, timing, structure, or purpose, you get entitlement, confusion, or avoidance instead of preparation.
So yes, the transfer is real, and the numbers are large. Yet the bigger issue for you is not the headline total. It’s whether your family has prepared the people, not just the paperwork, to manage what is eventually passed down.
Why Do Families Struggle To Keep Wealth Beyond The Second Or Third Generation?
You’ve probably heard the claim that 70% of wealthy families lose their wealth by the second generation and 90% by the third. That figure is widely repeated in wealth management and estate-planning circles, and CFA Institute notes how often it appears in industry discussion. At the same time, it also points out that the statistic is not always backed by transparent, modern, peer-reviewed evidence. So you shouldn’t treat it as a precise law of finance. You should treat it as a warning about recurring family patterns.
Those patterns are familiar to anyone who has spent time around estate disputes, succession planning, or inherited wealth. Families fail to communicate early. Children grow up shielded from financial decisions, then are expected to manage trusts, property, investments, or operating businesses overnight. Parents assume legal documents will carry values forward on their own. Siblings interpret fairness differently. One heir wants income, another wants control, another wants to liquidate. The money becomes a pressure point because the family never built a working process around it.
This is why wealth often disappears without a market crash or a single reckless decision. It erodes through fragmented decisions, poor coordination, inconsistent values, weak boundaries, and a lack of financial competence. You don’t need a dramatic failure for wealth to vanish. You just need years of unmanaged withdrawals, tax inefficiency, bad lending within the family, uneven risk-taking, and silence around expectations.
If you want a better lens, stop asking whether the curse is “real” in a slogan-driven way. Ask whether your family is building financial judgment, trust, role clarity, and decision rules across generations. That is the real test. When those elements are missing, wealth preservation becomes luck, and luck doesn’t last.
What Role Do Wills, Trusts, And Estate Plans Play In Preserving Wealth?
Wills, trusts, beneficiary designations, powers of attorney, and related estate documents matter because they create continuity. They direct assets, reduce confusion, and can prevent delays that drain families emotionally and financially. Yet these tools are often overestimated. If your heirs don’t understand what documents exist, who holds authority, how distributions work, or what the long-term goals are, the legal structure may transfer wealth without preserving it.
That gap is bigger than many people think. Pew Research Center found that about 32% of United States adults say they have created a will, and rates vary sharply by age and income. Among adults in their 70s, about 66% say they have a will, while only about a third or fewer of adults under 60 have created one. Higher-income households report much higher completion rates than lower-income households, which means readiness for wealth preservation is uneven long before any inheritance enters the picture.
This is where many families get tripped up. They assume estate planning is the finish line, when it’s really the transfer mechanism. A will can say where assets go. A trust can define control, timing, and conditions. A power of attorney can help during incapacity. Still, none of those documents teach your beneficiaries how to manage distributions, evaluate investment decisions, handle family property, or work through disagreement.
You should treat estate planning as one layer of preservation, not the whole structure. The documents matter. They can reduce probate friction, protect minors, support privacy, and create management continuity. Yet if you stop there, you’ve built a bridge with no training for the people who have to cross it.
Why Is Family Communication A Core Part Of Financial Education?
Most wealth-preservation failures don’t start with markets. They start with silence. When families avoid money conversations, the next generation usually receives fragments instead of guidance: a rumor about a trust, a vague promise about property, a sense that “everything is handled,” and no working knowledge of what that means. Silence creates room for bad assumptions, resentment, and expensive mistakes.
Family communication is financial education because it gives meaning to the numbers. It explains why assets were structured a certain way, what the family wants to preserve, how philanthropy fits in, what spending discipline looks like, who makes which decisions, and what fair treatment means in practice. If you skip that work, heirs may interpret structure as mistrust, or they may view inherited assets as personal spending capacity rather than long-term capital that needs management.
Public reporting and industry guidance keep returning to this point. Kiplinger has emphasized that communication is central to a successful legacy, and family-meeting guidance from private wealth firms shows why: regular conversations expose younger generations to financial issues early, create a forum for discussing long-term goals, and help cement the values tied to preserving wealth. When you meet regularly, the family stops relying on whispered updates and starts building a shared language around stewardship.
You don’t need to turn every dinner into a balance-sheet review. You do need a repeatable communication rhythm. Without it, even a well-funded family can become disorganized fast. With it, your heirs gain clarity, vocabulary, and enough confidence to make decisions without blowing up relationships.
How Can You Use Family Meetings To Teach Stewardship Across Generations?
Family meetings work because they move education out of theory and into practice. A regular meeting gives you a forum to explain what the family owns, what it values, what responsibilities come with that ownership, and how decisions will be made. Commerce Trust points out that family meetings can provide a regular place to discuss finances and long-term goals, engage younger generations, and prepare them to participate in decisions related to family wealth.
You should keep these meetings structured, calm, and useful. Set an agenda. Define who attends. Decide which topics are informational and which require decisions. Cover the basics first, cash flow, trusts, investment principles, estate roles, charitable priorities, real estate responsibilities, family business updates, and any upcoming transitions. If the family is large or tensions already exist, start with a smaller core group and expand participation over time.
The value of these meetings is not just information transfer. It is role training. Younger family members learn what a trustee does, why liquidity matters, how risk is discussed, why taxes affect decision timing, and what responsible distributions look like. They also learn how to ask questions in a setting that doesn’t punish curiosity. That matters more than people realize. Financial silence often produces shame, and shame keeps heirs uninformed until they are suddenly in charge.
You can also use meetings to hand out responsibility in measured ways. Let younger members review a charitable budget, help organize records, participate in education sessions with advisors, or track a family property budget. Stewardship grows when responsibility is earned in stages. If you wait until a death or disability forces the issue, you’ve waited too long.
What Should Financial Education Cover If Your Goal Is Long-Term Wealth Preservation?
If your goal is preserving wealth across generations, financial education needs to go beyond personal budgeting. You should teach four layers: personal capability, investment competence, legal continuity, and family governance. Miss any one of those, and the whole system gets weaker. This is where many otherwise smart families leave a hole in the plan.
The first layer is personal capability. That includes budgeting, cash-flow management, debt discipline, emergency reserves, insurance awareness, taxes, and everyday decision-making. This sounds basic, yet basic failures ruin inherited wealth all the time. A beneficiary who cannot manage recurring expenses, credit use, and liquidity will often treat distributions as income relief instead of capital that requires discipline.
The second layer is investment competence. You need heirs to understand asset allocation, diversification, volatility, liquidity, time horizon, and the difference between spending assets and productive assets. They do not need to become portfolio managers. They do need enough fluency to ask solid questions, evaluate advice, and avoid panic decisions. This is where the Personal Finance Index categories around investing, risk, and information-gathering become especially relevant.
The third layer is legal continuity. Your family should understand the purpose of wills, trusts, beneficiary designations, powers of attorney, healthcare directives, and titling. They should know who to contact, where documents are stored, what happens when someone becomes incapacitated, and what role each decision-maker plays. Confusion here causes delays, conflict, and legal bills that could have been prevented with one afternoon of orientation.
The fourth layer is family governance. This covers how your family makes decisions, resolves disputes, documents values, discusses fairness, sets distribution expectations, and defines responsibilities tied to shared wealth. This may include family councils, meeting cadences, education plans for heirs, philanthropic decision rules, and processes for business or property decisions. Money without governance produces friction. Money with governance gives you a system that can hold up under pressure.
How Do You Turn Financial Knowledge Into A Working Wealth-Preservation System?
Knowledge becomes preservation only when you build systems around it. That means written plans, recurring education, clear ownership records, documented contacts, and decision rules that the family can actually follow. The reason many households struggle is not that nobody has ever heard of budgeting, investing, or estate planning. It’s that the knowledge stays scattered, informal, and person-dependent. Once the main decision-maker is gone, the structure falls apart.
Start by documenting the financial map. List key accounts, real estate, business interests, insurance policies, legal entities, estate documents, advisor relationships, and major obligations. Then document who is responsible for what. You need names, roles, access points, and instructions. This sounds simple, yet it removes a large share of the chaos families face during transitions.
Then implement an education rhythm. Annual is a minimum for many families, though more frequent discussions can work better when transitions are approaching or younger heirs are being brought in. Build a learning agenda that matches age and responsibility. Teenagers can learn budgeting, saving, and charitable giving. Young adults can learn taxes, credit, and retirement accounts. Adult heirs can learn trust structures, property management, investment policy, and family governance rules.
You should also run decision reviews. If the family made a major purchase, sold property, updated an estate plan, or adjusted an investment strategy, explain why. This is how judgment gets transferred. Heirs do not learn stewardship from slogans about “working hard” or “being responsible.” They learn it by seeing how disciplined decisions are made, documented, and revisited over time.
When you build a working system, wealth becomes less dependent on memory, personality, or hierarchy. That is a real upgrade. It makes the family more resilient, and it reduces the chance that one illness, one conflict, or one uninformed beneficiary derails years of planning.
How Do You Preserve Generational Wealth?
- Teach money skills early.
- Create wills, trusts, & beneficiary plans.
- Hold regular family meetings.
- Train heirs on investing, taxes, & stewardship.
- Document roles, values, and decision rules.
Protect The Wealth By Preparing The People
If you want wealth to last, you can’t treat education as an optional add-on after the legal work is finished. You need financial literacy, estate planning, communication, and governance working together, or the handoff will stay fragile. The data on financial capability, emergency savings, financial literacy, and will ownership all point in the same direction: families are often less prepared than they assume. Your edge comes from building skill before the transfer, clarity during the transfer, and disciplined systems after the transfer. Keep the plan practical, repeat the conversations, and train heirs in stages. That’s how you give the next generation more than money, you give them the capacity to keep it.
References
- FINRA Foundation, The National Financial Capability Study — https://www.finrafoundation.org/national-financial-capability-study
- TIAA Institute and Global Financial Literacy Excellence Center, Personal Finance Index — https://www.tiaa.org/public/institute/focus/personal-finance-index
- FINRA, National Study by FINRA Foundation Finds More U.S. Households Struggling Financially Despite Stable Incomes — https://www.finra.org/investors/insights/finra-foundation-national-financial-capability-study
- Kiplinger, Why Wills and Trusts Aren’t Enough in the Great Wealth Transfer — https://www.kiplinger.com/retirement/estate-planning/wills-and-trusts-arent-enough-in-the-great-wealth-transfer
- CFA Institute, Dispelling Myths About the Great Wealth Transfer — https://www.cfainstitute.org/insights/articles/great-wealth-transfer-myths-reality
- CFA Institute, How Real Is the Third-Generation Curse? — https://www.cfainstitute.org/insights/articles/third-generation-wealth-curse-advisor-solutions
- Pew Research Center, Experiences With Estate Planning and Discussing End-of-Life Preferences — https://www.pewresearch.org/social-trends/2025/11/06/experiences-with-estate-planning-and-discussing-end-of-life-preferences/
- Commerce Trust, Family Meetings for High-Net-Worth Families — https://www.commercetrustcompany.com/research-and-insights/articles/communicating-your-legacy-with-family-meetings